Insurance7 min
How to file a roof insurance claim in Texas
The claim process, step by step: what your policy actually covers, what the adjuster is looking for, and the mistakes that get claims denied.
Erin Vasquez
Co-founder & Head of Operations
What your policy covers
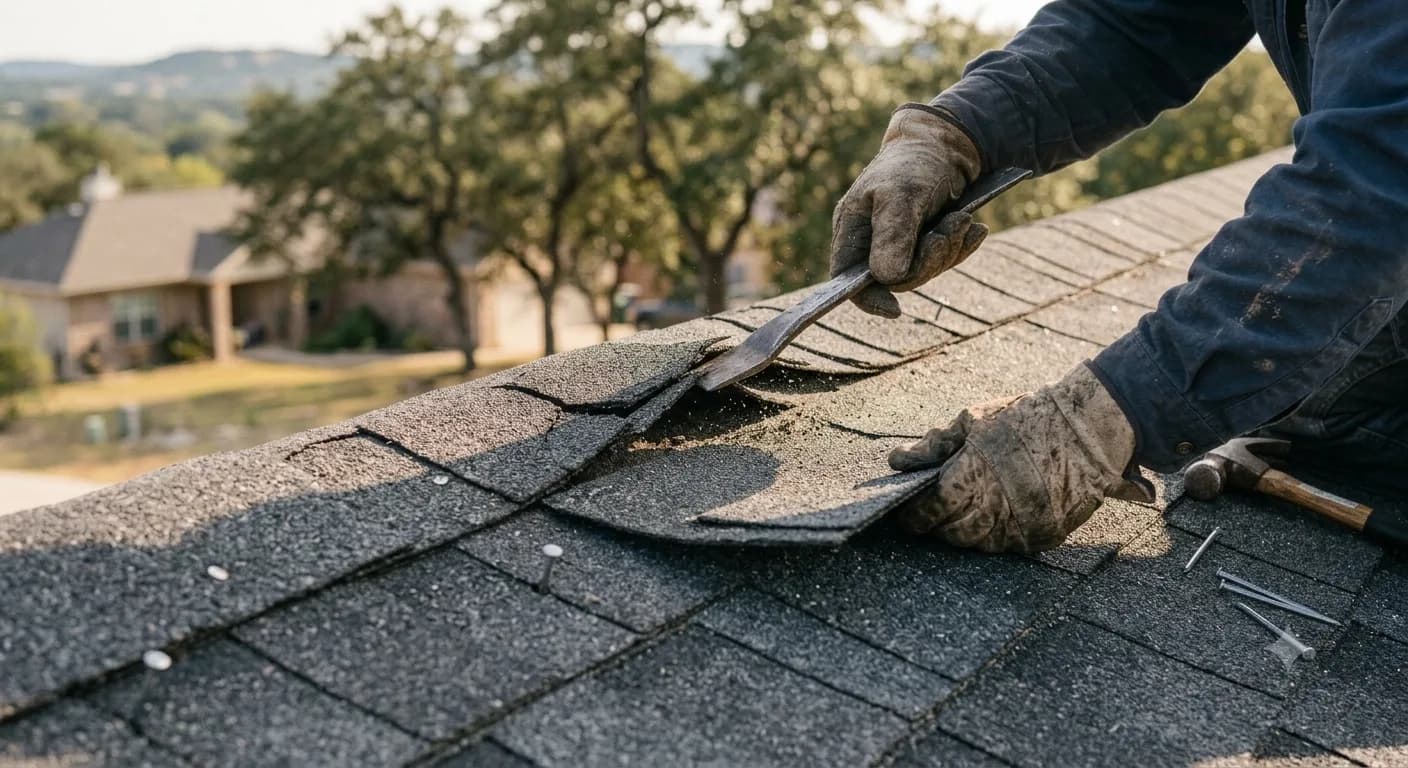
Most Texas homeowner policies cover sudden storm damage from hail, wind and fallen limbs, but not wear and age. That line matters: the insurance company pays to fix what the storm did, not to replace an old roof. A good damage report draws that line clearly, with photos.
Step one: document before you touch anything
Photograph everything the day of the storm if it's safe: hail on the ground next to a coin, dented gutters, shingles in the yard. Dated photos from day one are the strongest evidence your claim will ever have.
Step two: get an inspection before you call
Call a local roofer before you call your insurance company. Here's why: once you file, the clock starts and an adjuster gets assigned. Walking into that meeting with a professional photo report means the conversation starts from evidence. If there's no real damage, you've also avoided filing a claim that raises your premium for nothing.
Step three: file promptly
Most Texas policies require what they call "prompt notice" after a storm. Your policy will say how long you have, so check it and don't sit on it. File with your policy number, the storm date, and your inspection report attached.
Step four: the adjuster meeting
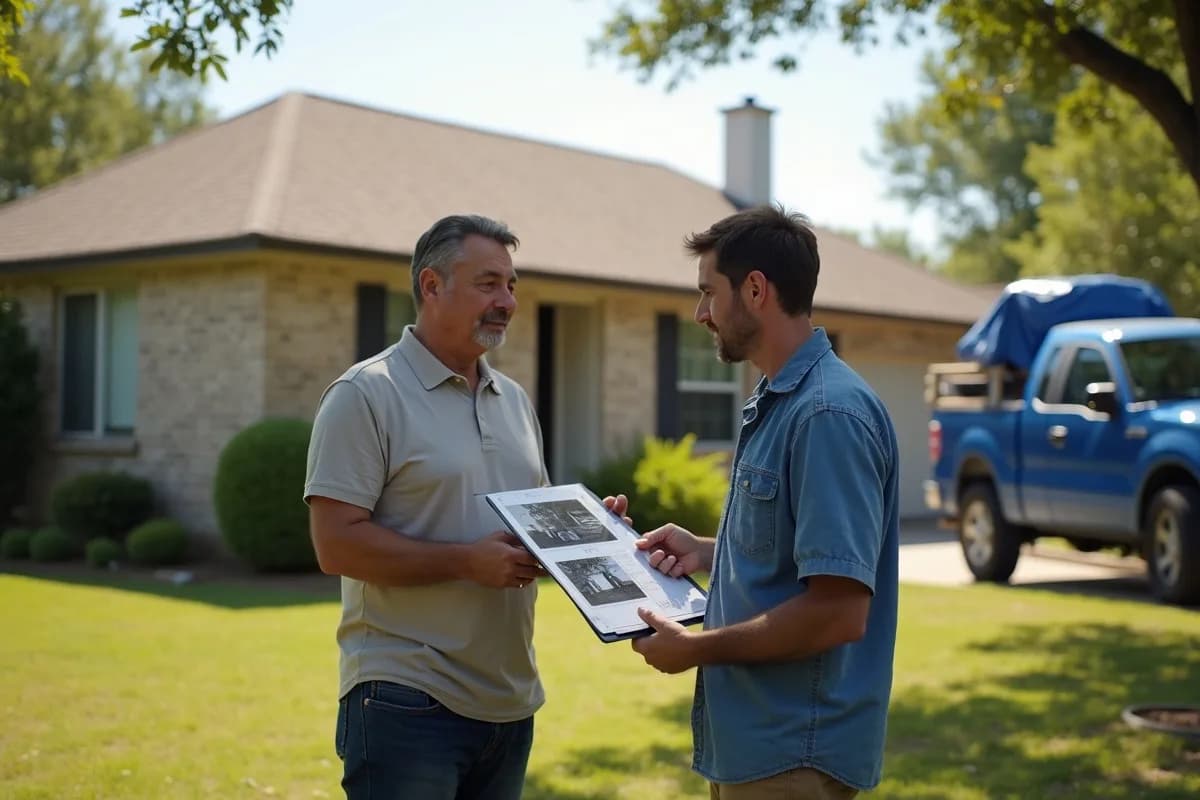
The adjuster walks your roof and writes their own damage scope. Have your roofer there. When our estimator meets the adjuster on the roof with our report in hand, the two scopes usually match by the end of the visit, and matching scopes mean fast approvals. Most claims we work are approved within two weeks.
Step five: read the settlement
You'll get an approval with two numbers: the actual cash value (paid now) and the recoverable depreciation (paid when the work is done). Your real out-of-pocket cost on an approved claim is usually just your deductible.
The mistakes that get claims denied
Waiting a year to file. Patching the roof before anyone documents it. Signing an assignment-of-benefits form with a door-knocking crew. Accepting the first scope without your own report to compare it against.
One rule of thumb
The homeowner with a dated photo report gets a very different claim experience than the homeowner with a hunch. Get the free inspection first. It's the single most important step in the whole process.